Low-latency trading and risk terminal
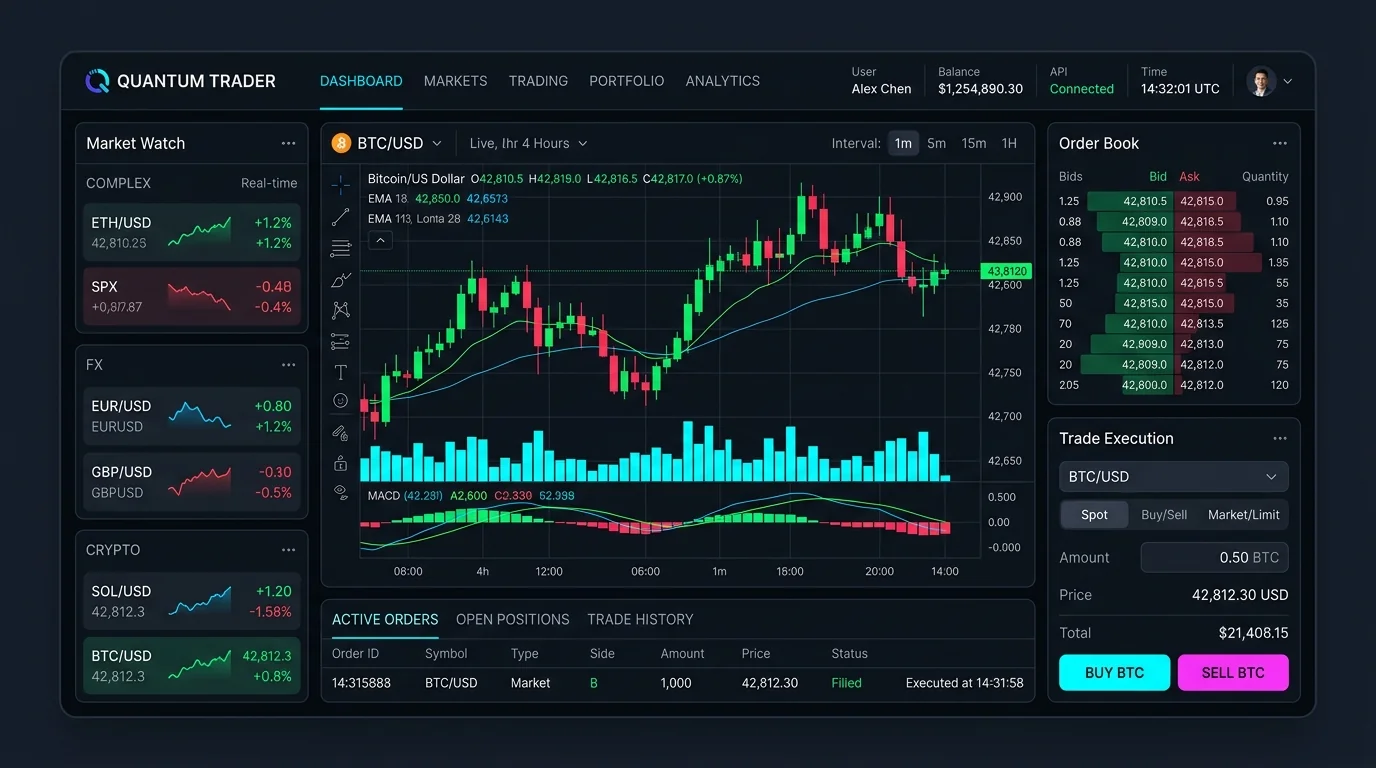
QuantStream needed a trading terminal that processed 85,000 market ticks per second, showed Level-2 order depth, and supported low-latency risk controls.
Context image for this case study; it does not depict the delivered software interface.
Our Contribution
Bitneka built the trading interface, market-data pipeline, and order-risk services for quantitative trading.
Challenge and Solution
Combining live market depth, high-volume tick processing, and low-latency execution with clear risk controls.
The Problem
Off-the-shelf trading terminals were unable to render intense order book tick velocity without crashing browser tabs. Quantitative traders needed sub-millisecond execution telemetry and real-time portfolio VaR (Value at Risk) risk checks.
- Browser DOM collapsing under 85,000 continuous WebSocket price updates per second.
- High financial risk during market flash crashes requiring instant automated kill-switch circuit breakers.
- Real-time backtesting of complex quantitative strategies across 10 years of tick data.
Our Solution
Bitneka Technologies developed an ultra-high-throughput financial terminal utilizing WebGL canvas rendering, memory-mapped shared buffers via WebAssembly, and a core execution backend written in Rust.
- Sub-8ms round-trip order execution speed via co-located Equinix LD4 and NY4 data center servers.
- 60fps WebGL order book depth visualizer processing 85,000 ticks/sec with zero CPU thermal throttling.
- Hardware-level automated kill-switch circuit breaker executing portfolio liquidation within 2 milliseconds of risk breach.
How We Delivered
The team mapped market-data and execution paths, built the terminal and risk controls, tested latency, and prepared production deployment.
Tick Engine Architecture
Engineered memory-efficient binary flatbuffer serialization over high-speed WebSockets.
WebGL Canvas Renderer
Custom WebGL rendering pipeline for order book depth charts, tick waterfalls, and DOM ladders.
Rust Core Execution
Built multi-threaded Rust execution workers with lock-free ring buffers connected to exchange gateways.
Production Hardening
Conducted live algorithmic trading simulation across $500M in test orders under chaotic market conditions.
High-Frequency Order Book & Execution Architecture
Ultra-low-latency in-memory limit order book matching bids and asks at sub-50 microsecond latency with zero lock contention.
-
Stage 01
Market Data Multicast
Binary ITCH Feed Ingest via Kernel Bypass
< 15µs Ingestion -
Stage 02
Memory Order Book Core
Cache-Friendly Ring Buffer Order Book
C++ / Go Low-Alloc -
Stage 03
Microsecond Matcher
Price-Time Priority Continuous Matching
< 42µs Match Time -
Stage 04
Smart Venue Execution
Cross-Exchange Arbitrage & Algorithmic Slice
Zero Queuing Lag -
Stage 05
Drop-Copy Audit Log
Immutable Real-Time Execution Log to Disk
100% Deterministic
What We Built
Zero-allocation in-memory order book matching, FIX 4.4 / WebSocket gateway, and automated risk liquidation engine.
Sub-8ms Order Routing
Direct market access (DMA) via optimized binary protocols to major equities and crypto liquidity pools.
Level-2 60fps Depth-of-Market Ladder
Renders full 100-level deep order books with cumulative bid/ask wall volume bars.
Hardware Risk Kill-Switch
Automated circuit breaker instantly cancels all open orders if drawdown or delta exposure exceeds limits.
Python / C++ Algo Sandbox
Deploy algorithmic trading bots directly into execution sandboxes with live backtesting metrics.
Real-Time Portfolio VaR Heatmap
Calculates Value at Risk (VaR), portfolio beta, and delta-gamma exposure on every tick.
Nanosecond Tick Replay Terminal
Replay historical flash-crash events tick-by-tick to evaluate algorithmic response.
Technology Used
Rust low-latency execution engine, Chronicle Queue memory-mapped messaging, and React trading terminal.
Frontend & UI
Backend & APIs
Data & AI Layer
Cloud & DevOps
Results
Peak order matching throughput and tick-to-trade latency recorded during extreme crypto market volatility.
About these results: Figures cover execution latency, market data volume, trading flow, and risk-stop outcomes. Reporting periods can differ by measure; confidential implementation details are summarized.
"Bitneka Technologies built what standard financial vendors said could not be done in a web-based terminal. It processes 85,000 ticks a second with zero lag, and our execution speed gives our quantitative strategies a decisive edge in global markets."
Related Case Studies
Planning a trading or market-data system?
Share your feed, execution, and risk-control requirements. We can discuss an architecture suited to your operating conditions.